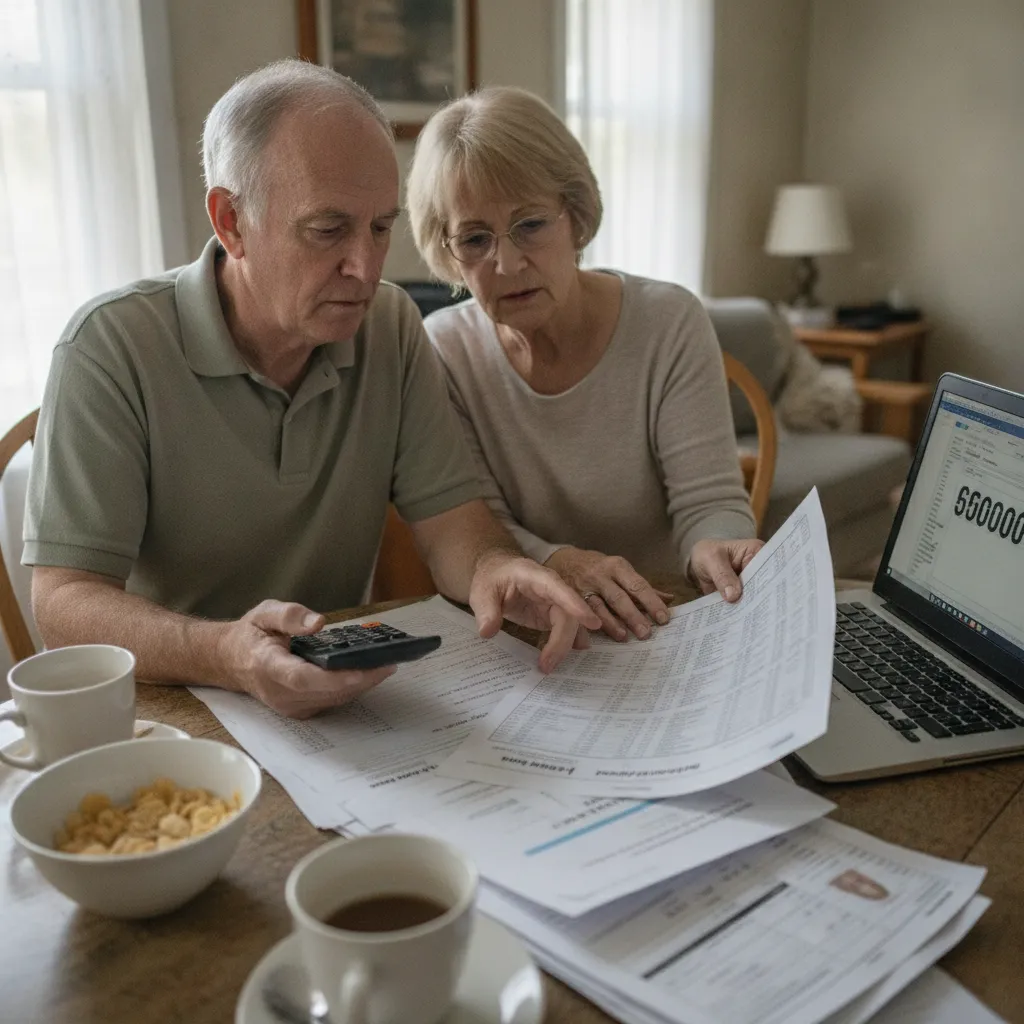
Hitting the two million dollar mark in retirement savings is a milestone that places an individual among the wealthiest ten percent of Americans. On paper, reaching a seven figure nest egg feels like crossing the finish line, providing a sense of security that few ever achieve. However, financial experts warn that being ahead of the average American does not necessarily mean you are ready to stop working. The reality is that a portfolio balance is merely one piece of a larger puzzle, and whether that money lasts depends less on the total sum and more on how it interacts with your specific lifestyle choices.
Consider two hypothetical couples who both enter retirement with two million dollars. One couple lives in a paid off home and relies on a combination of Social Security and a modest pension to cover most of their basic needs. Because their guaranteed income handles the bulk of their expenses, they only need to draw a small fraction of their investments each year to maintain their quality of life. This creates a safety buffer, allowing them to weather market crashes or medical emergencies without risking bankruptcy. For them, two million dollars is more than enough because their cost of living remains low and predictable.
In contrast, another couple with the same amount of wealth may find themselves struggling if they maintain high spending habits or carry significant debt. If they are still paying off a primary mortgage while dreaming of purchasing luxury vacation properties, that seven figure cushion evaporates quickly. When someone attempts to fund an expensive lifestyle solely through investment withdrawals—especially while taking large lump sums for real estate—they risk pushing their withdrawal rate far beyond sustainable levels. Unlike fixed costs like mortgages and taxes, investment returns fluctuate; those who overextend themselves leave no room for error when the market dips.
Ultimately, the goal of retirement planning should not be to hit a magic number or outperform the national average, but rather to calculate the gap between desired spending and guaranteed income. A portfolio exists simply to fill that void. Whether two million dollars represents absolute freedom or a precarious tightrope depends entirely on how much work you ask your money to do every month. Instead of comparing balances with neighbors, retirees must focus on their actual cash flow and daily expenditures to determine if they can truly afford to walk away from their careers.